Cigna raises its 2026 outlook as insurance growth offsets a weaker pharmacy unit
Adjusted earnings of $7.98 a share topped the $7.46 Zacks consensus, and Cigna now sees at least $30.60 a share for the year.
By Marcus Rodriguez ·
Why it matters: Cigna's growth is coming from its health plans and specialty care, not its pharmacy benefits arm, which is losing customers.
For information only, not investment advice. Prices delayed.
Tickers: CI
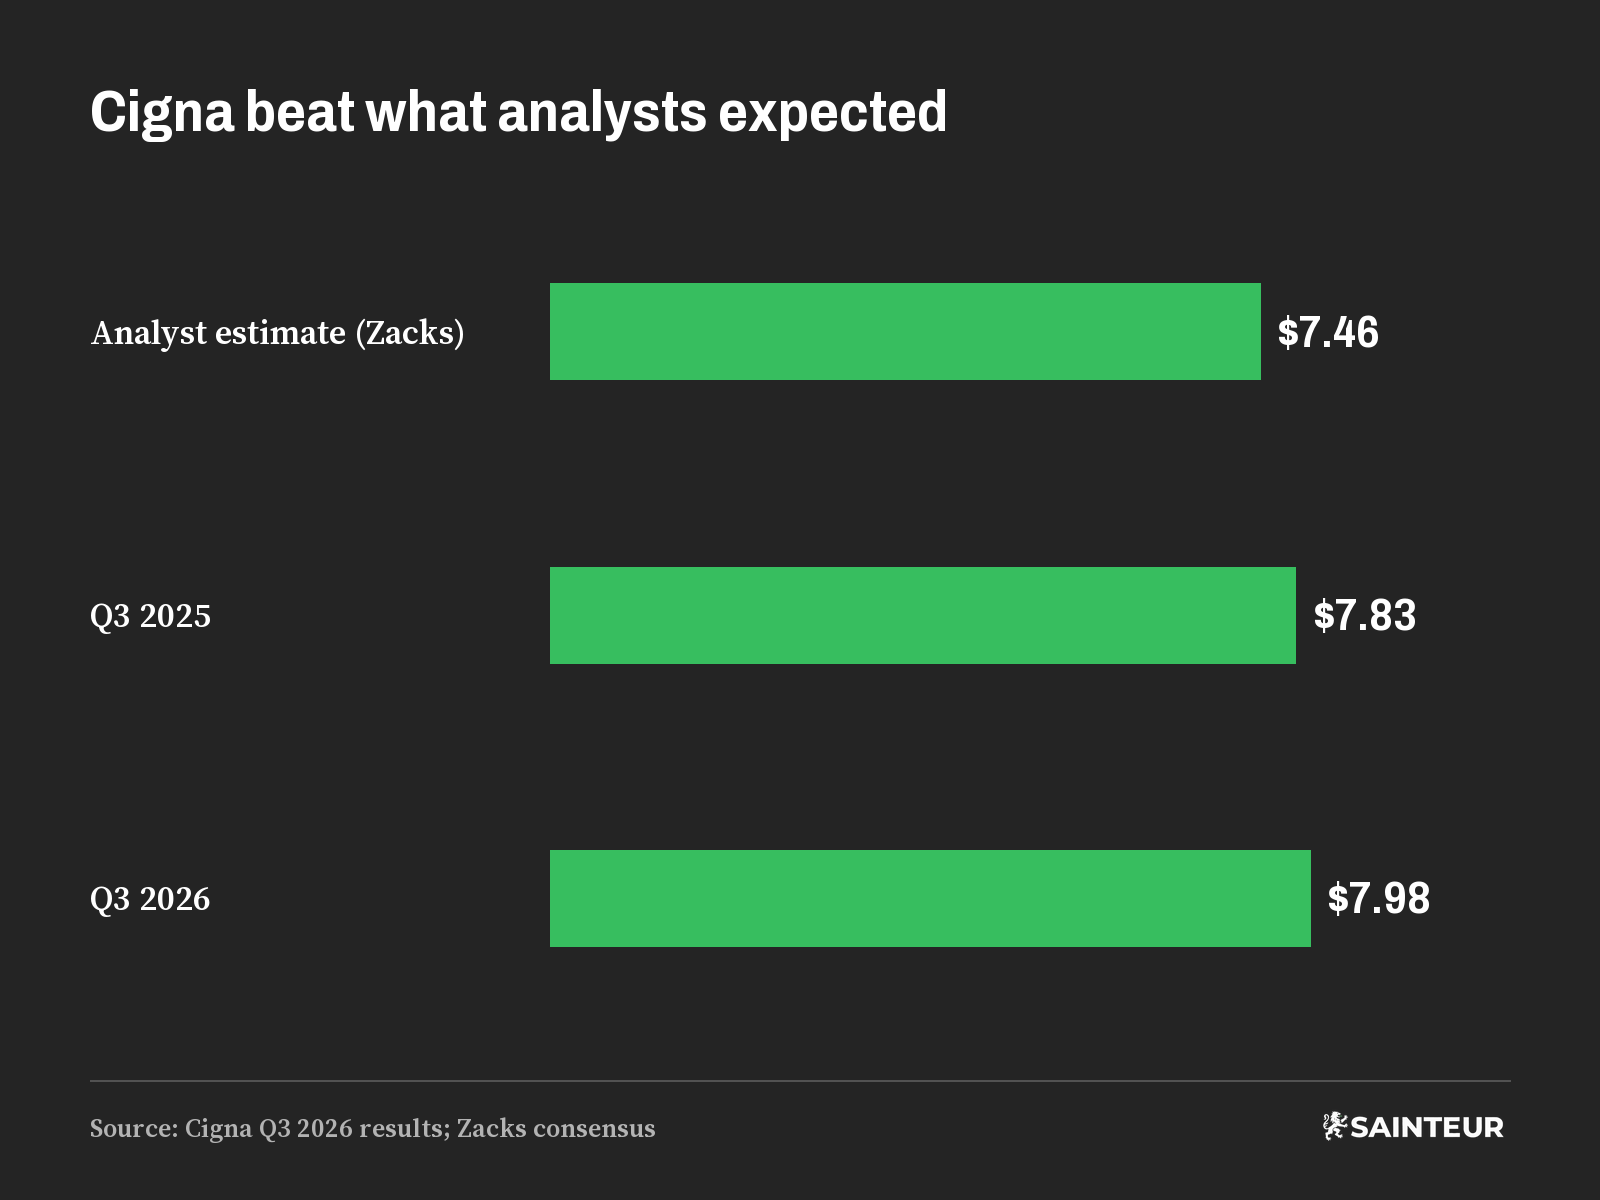
The Cigna Group ($CI), the health insurer and pharmacy benefit manager, beat Wall Street's third-quarter expectations. Adjusted earnings came to $7.98 a share, up from $7.83 a year earlier.[^1] The average estimate of seven analysts surveyed by Zacks Investment Research was $7.46.[^2] Cigna now expects 2026 adjusted income from operations of at least $30.60 a share, $0.15 above its prior projection.[^1]
Underneath, the insurance side did the heavy lifting. Strong growth in Cigna Healthcare and in Specialty and Care Services offset a lower contribution from Pharmacy Benefit Services, leaving adjusted income from operations stable at $2.1 billion versus a year earlier.[^1]
The customer counts show where the pressure sits. Pharmacy customers fell 5% from the end of 2025 to 117.7 million, which Cigna attributed to expected client transitions and lower membership from health plan clients, while medical customers rose 2% to 18.5 million.[^1]
On a GAAP basis, shareholders' net income fell to $1.4 billion, or $5.47 a share, from $1.9 billion, or $6.98, a year earlier. Cigna said that mainly reflects the absence of an after-tax gain on a sale booked in the 2025 quarter.[^1]
Sources
- The Cigna Group Reports Strong Third Quarter 2026 Results, Raises 2026 Outlook (Form 8-K, Exhibit 99.1), The Cigna Group
- Cigna: Q3 Earnings Snapshot, Associated Press via Yahoo Finance
Tags: earnings · guidance · healthcare-pharma